The Philippines Branded Residences Market Snapshot 2026 provides an overview of the country’s branded residences market. In 2026, the market reached PHP235.5 billion (USD3.8 billion) in value across 7,433 launched units, with supply concentrated in condominium developments across Metro Manila and Metro Cebu.
Investor Highlights
- Market Value, Launched Units and Unit Pricing
- Development Type and Chain Scale Positioning
- Supply by Product Type and Destination
- Metro Manila and Metro Cebu Supply Concentration
Supply Concentrates in Major Cities, Led by Mixed-Use and Upscale Developments
The Philippines’ branded residences market reached PHP235.5 billion (USD3.8 billion) across 7,433 launched units in 2026, the third-largest launched supply in Asia after Thailand and Vietnam. Within Asia’s USD40 billion branded residences market, up 30.3% year-on-year across 50,025 launched units, the Philippines ranks third by launched units yet fifth by market value, at an average USD514,000 per unit.
Supply is 97% condominiums, while landed properties and hybrid products remain the minority. By chain scale, the upscale tier holds the largest share at 66% of developments, while the luxury tier accounts for 26% of the 38 properties. The weighting toward upscale over luxury reinforces the market’s accessible, volume-driven positioning.
The development mix is led by mixed-use at 40% of units (4,866 units), ahead of projects co-located with a hotel at 33% and standalone at 27%, making Philippines one of Asia’s highest shares of mixed-use branded residences
Supply concentrates in the two largest metropolitan areas. Metro Manila leads with 39% of national supply (4,814 units) and Metro Cebu follows at 28%, together accounting for two-thirds of the Philippines’ 12,299 total supply units.
As high barriers to entry and a shortage of iconic locations push luxury developers to look beyond Phuket for top-end sites, ultra-luxury development is shifting north into Phang Nga’s oceanfront. The Khao Lak and Phang Nga Hotel & Tourism Market Review 2026 examines this shift across the province and its Khao Lak resort cluster. In Khao Lak, hotel performance trends are led by rate, with the average daily rate (ADR) up 26.2% year-on-year in the first quarter of 2026. Phang Nga tourism revenue reached THB56.6 billion (USD1.7 billion) in 2025 on 4.3 million visitor arrivals.
Key Sections Covered
- Khao Lak Hotel Performance Trends
- Phang Nga Tourism Demand, Visitor Arrivals and Tourism Revenue
- Phang Nga Southern Provinces Ranking
- Outlook and Phang Nga Hotel Pipeline
Investor Highlights
1. Khao Lak Hotel Performance Trends are Led by Rate, Not Volume
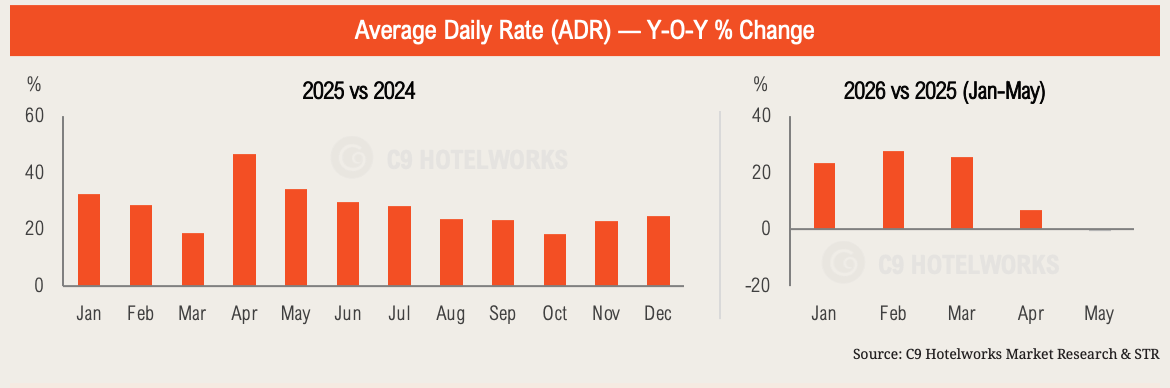
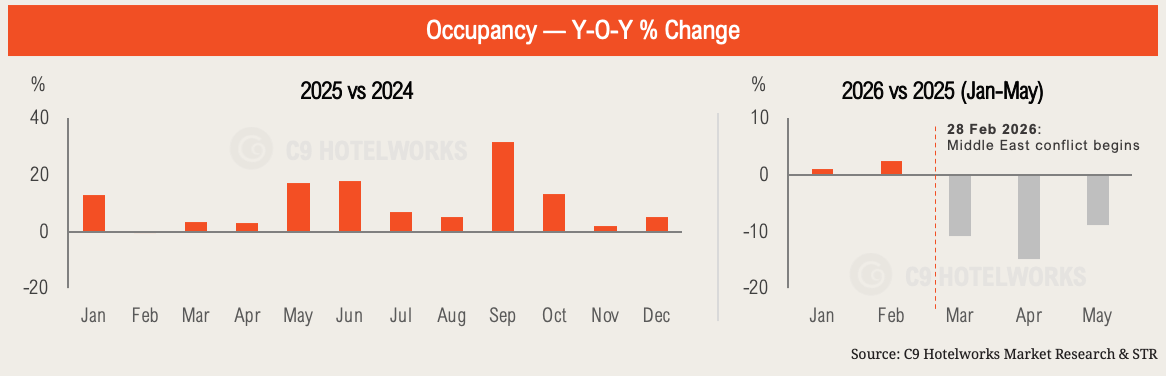
Average daily rate rose 26.2% year-on-year in the first quarter of 2026, extending 2025 gains, when monthly increases ranged from 18.2% to 46.4%. Occupancy, by contrast, turned negative year-on-year from March 2026, and revenue per available room (RevPAR) turned negative in April and May as the Middle East conflict and higher airfares softened international demand.
2. Visitor Arrivals Held Steady as the Wider Southern Region Contracted
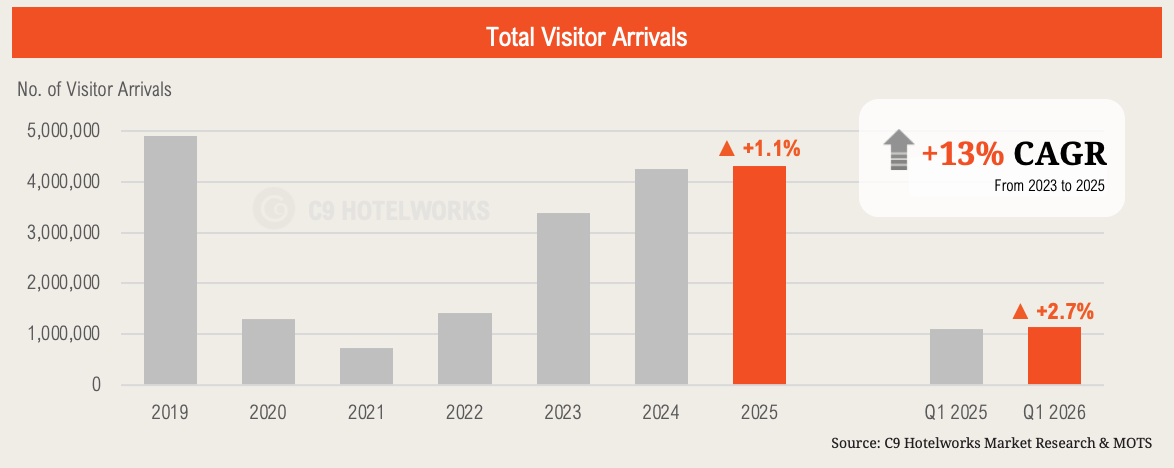
Phang Nga visitor arrivals reached 4.3 million in 2025, up 1.1% year-on-year and a 13% compound annual growth rate (CAGR) from 2023 to 2025, while Thailand’s Southern region (14 provinces) decreased by 0.6% over the same period. Tourism revenue rose 2% to THB56.6 billion (USD1.7 billion), ahead of the 1.1% increase in visitor arrivals.
The 2025 gain was domestic-led: international visitor arrivals held at 2.61 million, down 0.2%, while domestic visitor arrivals rose 3.2% to 1.7 million. Visitor arrivals rose a further 2.7% year-on-year in the first quarter of 2026, before international demand softened from March.
3. Phang Nga Ranks Fourth by Revenue but Sixth by Visitor Volume
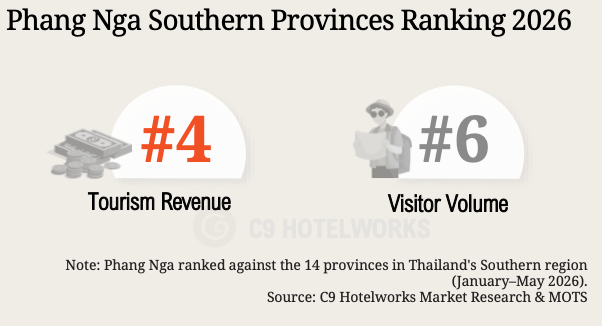
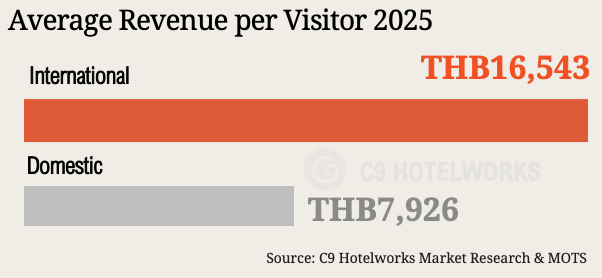
As of May 2026, Phang Nga ranked fourth of the 14 provinces in Thailand’s Southern region by tourism revenue, behind Phuket, Surat Thani and Krabi, but sixth by visitor volume, a sign of higher spending per visitor. In 2025, international visitors made up 61% of visitor arrivals but 76% of revenue, spending more than double per head (THB16,543) than domestic visitors (THB7,926). With 2025 growth outpacing a contracting region, this top-end positioning continues to draw luxury developers north from Phuket into Phang Nga.
4. The Outlook Points to Top-End Development Shifting North from Phuket into Phang Nga
As high barriers to entry and a shortage of iconic locations push luxury developers to look beyond Phuket for top-end sites, ultra-luxury development is shifting into Phang Nga Bay and the coastline north of the Sarasin Bridge, from Natai to Thai Muang, where oceanfront sites support full-service resorts rather than commoditized, box-type product. The active pipeline consists of 315 keys, led by the InterContinental Phang-Nga Bay Resort (150 keys, 2028) and Kimpton Natai (150 keys, 2027), alongside a 15-key expansion of Khaolak Paradise Resort in 2026.
Meanwhile, Khao Lak is maturing as a market, helped by four-lane access from Phuket International Airport and the 170-hectare Matalay integrated resort community, featuring five international-standard resort sites.
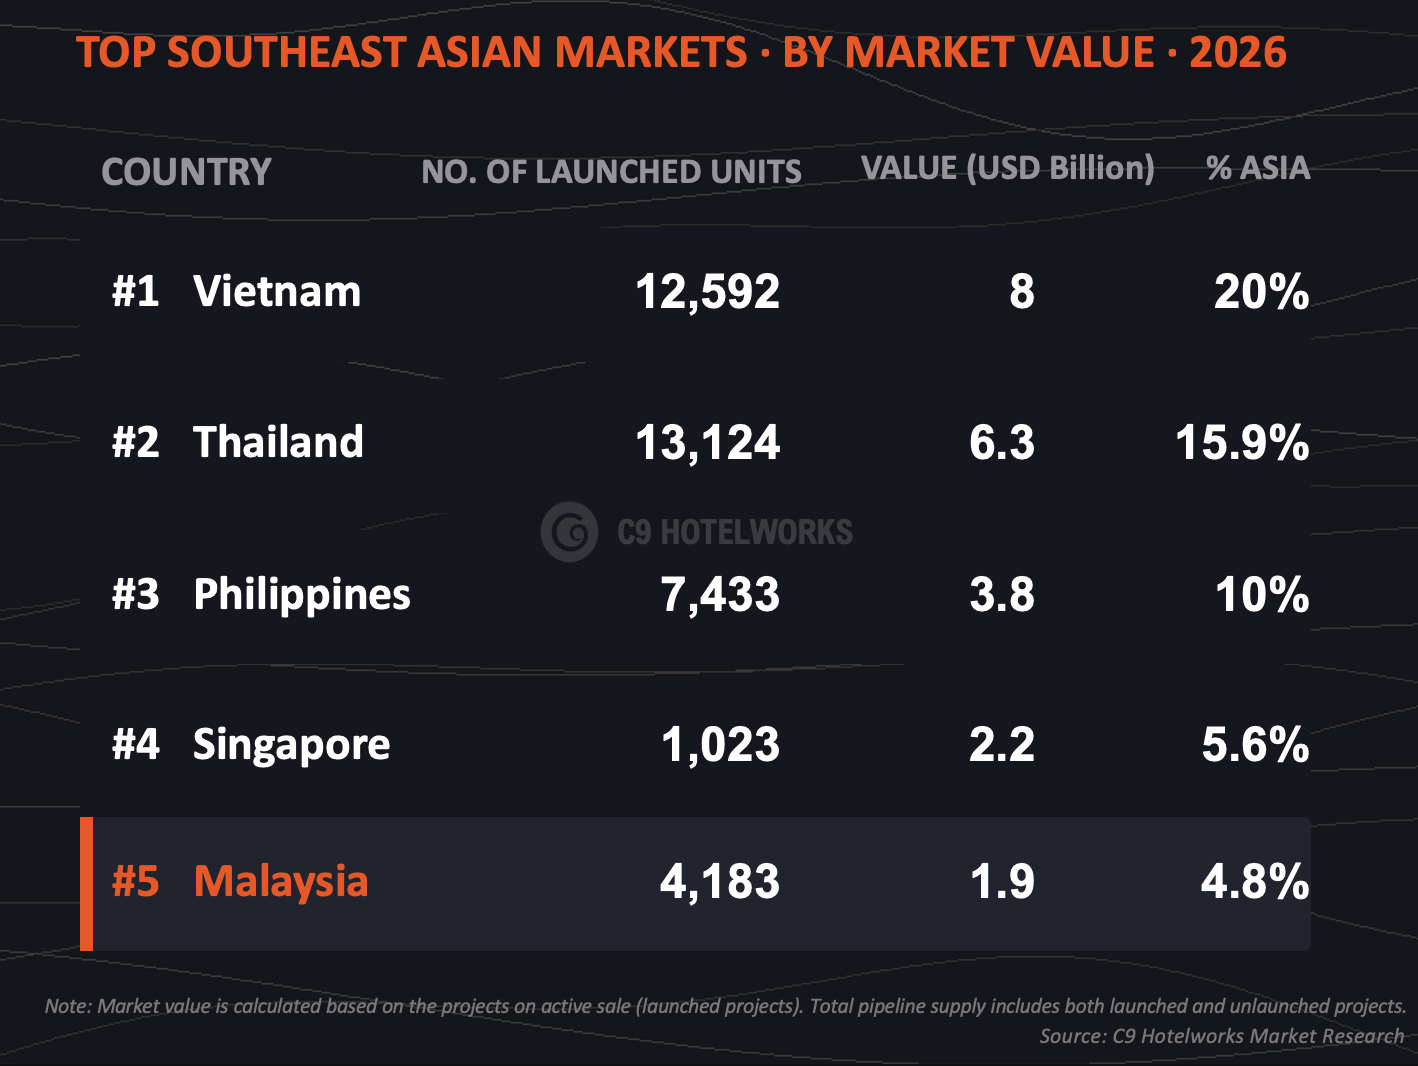
The Malaysia Branded Residences Market Review 2026 examines where Malaysia sits within Asia’s record USD40 billion branded residences market. Malaysia ranks fifth in Southeast Asia by market value, at USD1.9 billion across 4,183 launched units. Supply remains modest and urban-led, the resort segment is largely untapped, and the next growth cycle is building in Johor, backed by record state investment and new infrastructure.
Key Sections Covered
- Asia Branded Residences Market Overview and Malaysia’s Ranking
- Malaysia Supply Distribution and Chain Scale
- Branded Residence Sale Prices Across the Region
- Real Estate Demand and Price Bands
- Growth Drivers and the Investment Landscape
- Malaysia Outlook
Investor Highlight
1. Malaysia Ranks Fifth Among Southeast Asian Markets by Market Value
In 2026, Asia’s branded residences pipeline is valued at USD40 billion across 50,025 launched units, up 30.3% year-on-year, on a total pipeline of 64,581 units. Malaysia’s launched units carry a market value of USD1.9 billion, fifth among Southeast Asian markets by value, behind Vietnam, Thailand, the Philippines, and Singapore.
Malaysia’s total pipeline is 5,812 units (4,183 launched, 1,629 unlaunched), a 9% share of Asia by units. By market value it holds under 5% of the region, mid-sized by volume but below its regional peers by value.
2. Supply Is Concentrated, Urban-Led, and Anchored in the Upper Upscale Tier
Malaysia’s branded residences supply is urban-led (75%) and concentrated in condominiums (95%), led by Kuala Lumpur and Penang. This leaves the resort segment largely untapped.
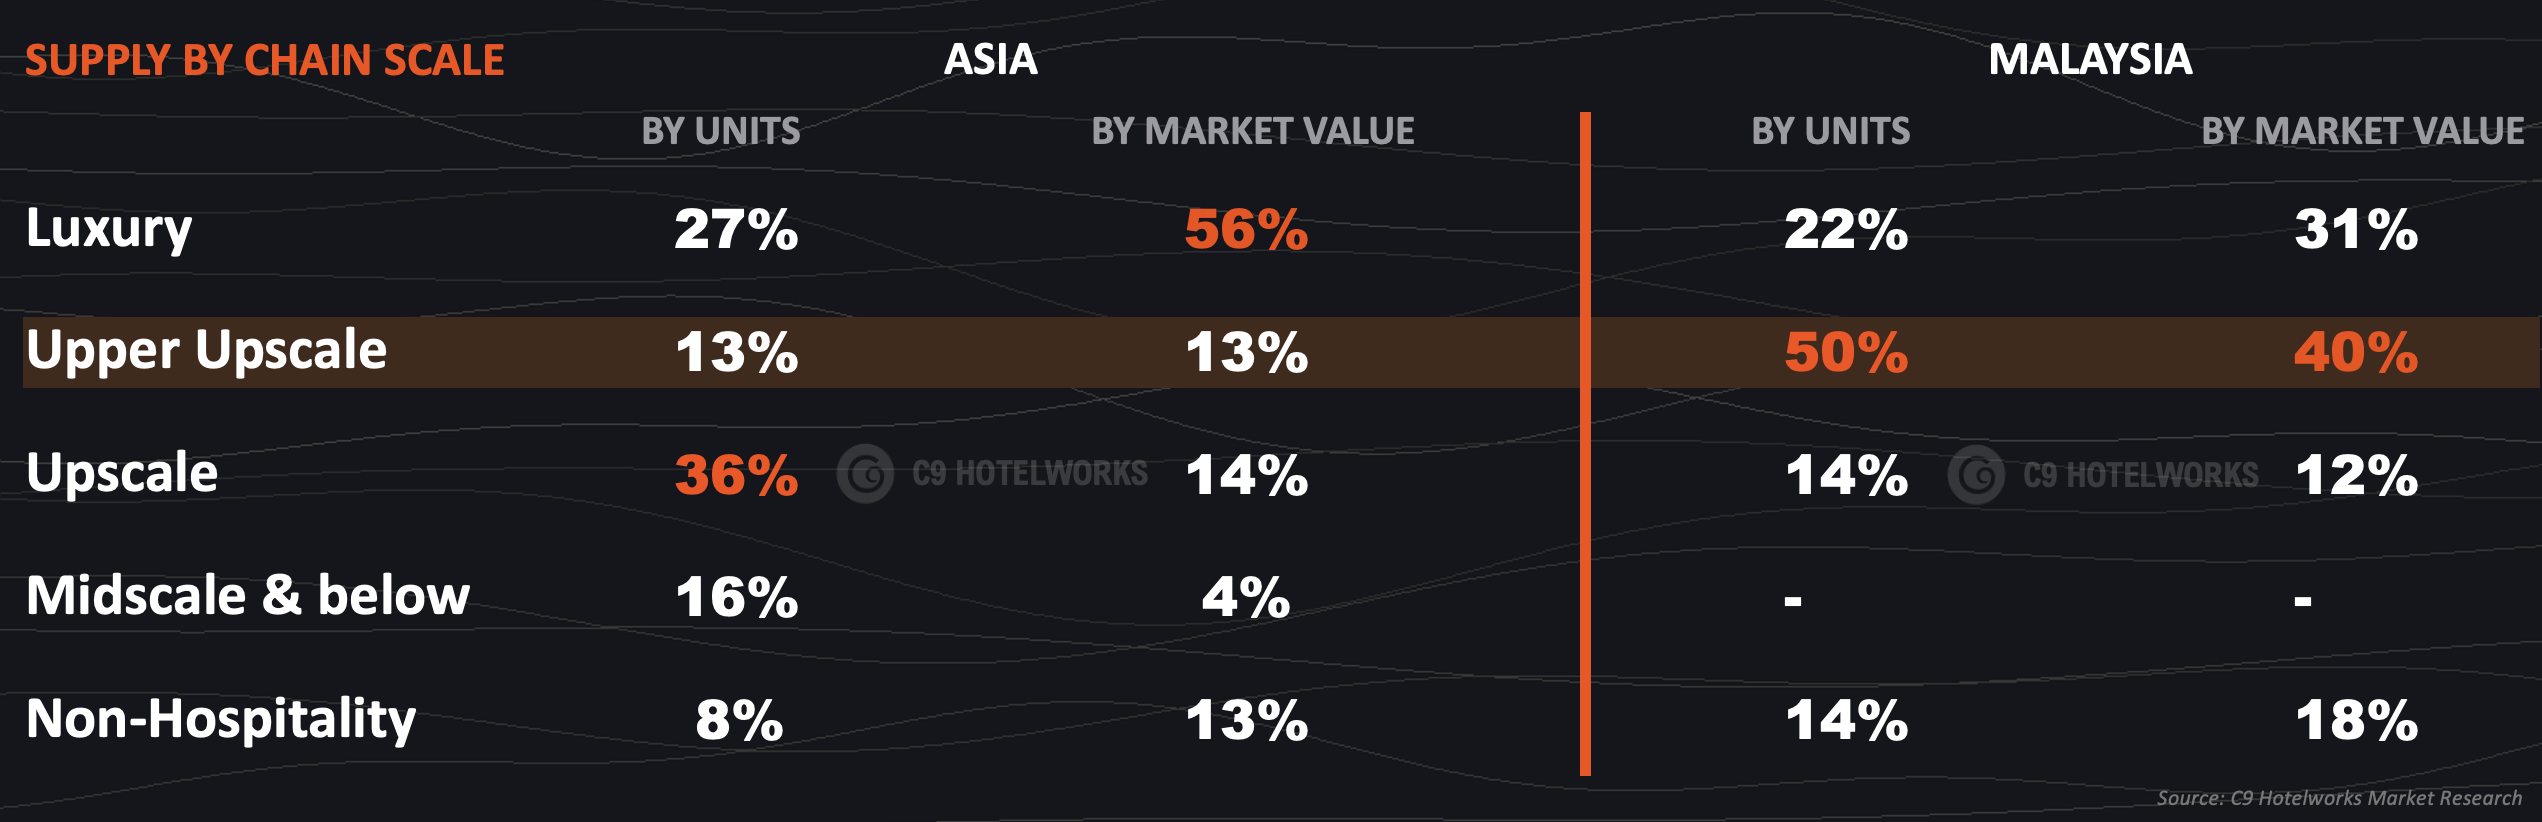
By chain scale, the upper upscale tier holds 50% of Malaysia’s branded units, against 13% across Asia. Malaysia is positioned a tier below the region, leaving room in the luxury tier, which remains thinner than the Asia benchmark.
3. Kuala Lumpur Is Competitively Priced Against the Region
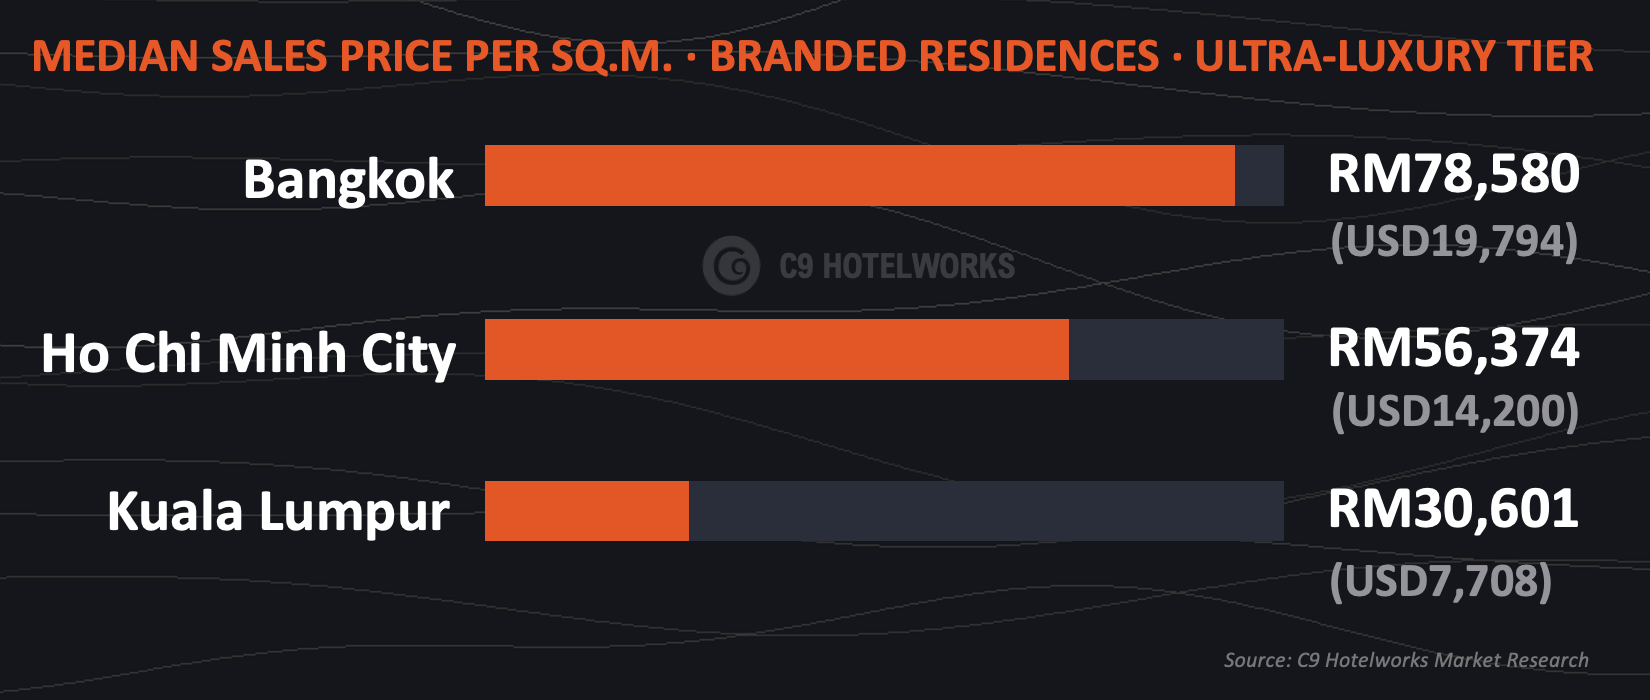
The median sales price per sq.m. for ultra-luxury branded residences places Kuala Lumpur at RM30,601 (USD7,708), against RM78,580 (USD19,794) in Bangkok and RM56,374 (USD14,200) in Ho Chi Minh City, a 2.6 times gap between Bangkok and Kuala Lumpur.
Malaysia My Second Home (MM2H) makes a property purchase compulsory, up to RM2 million at the top tier, which channels foreign demand toward the branded segment. The pricing position offers investors a value entry point relative to the region.
4. Domestic Demand Is Concentrating at the Top of the Market
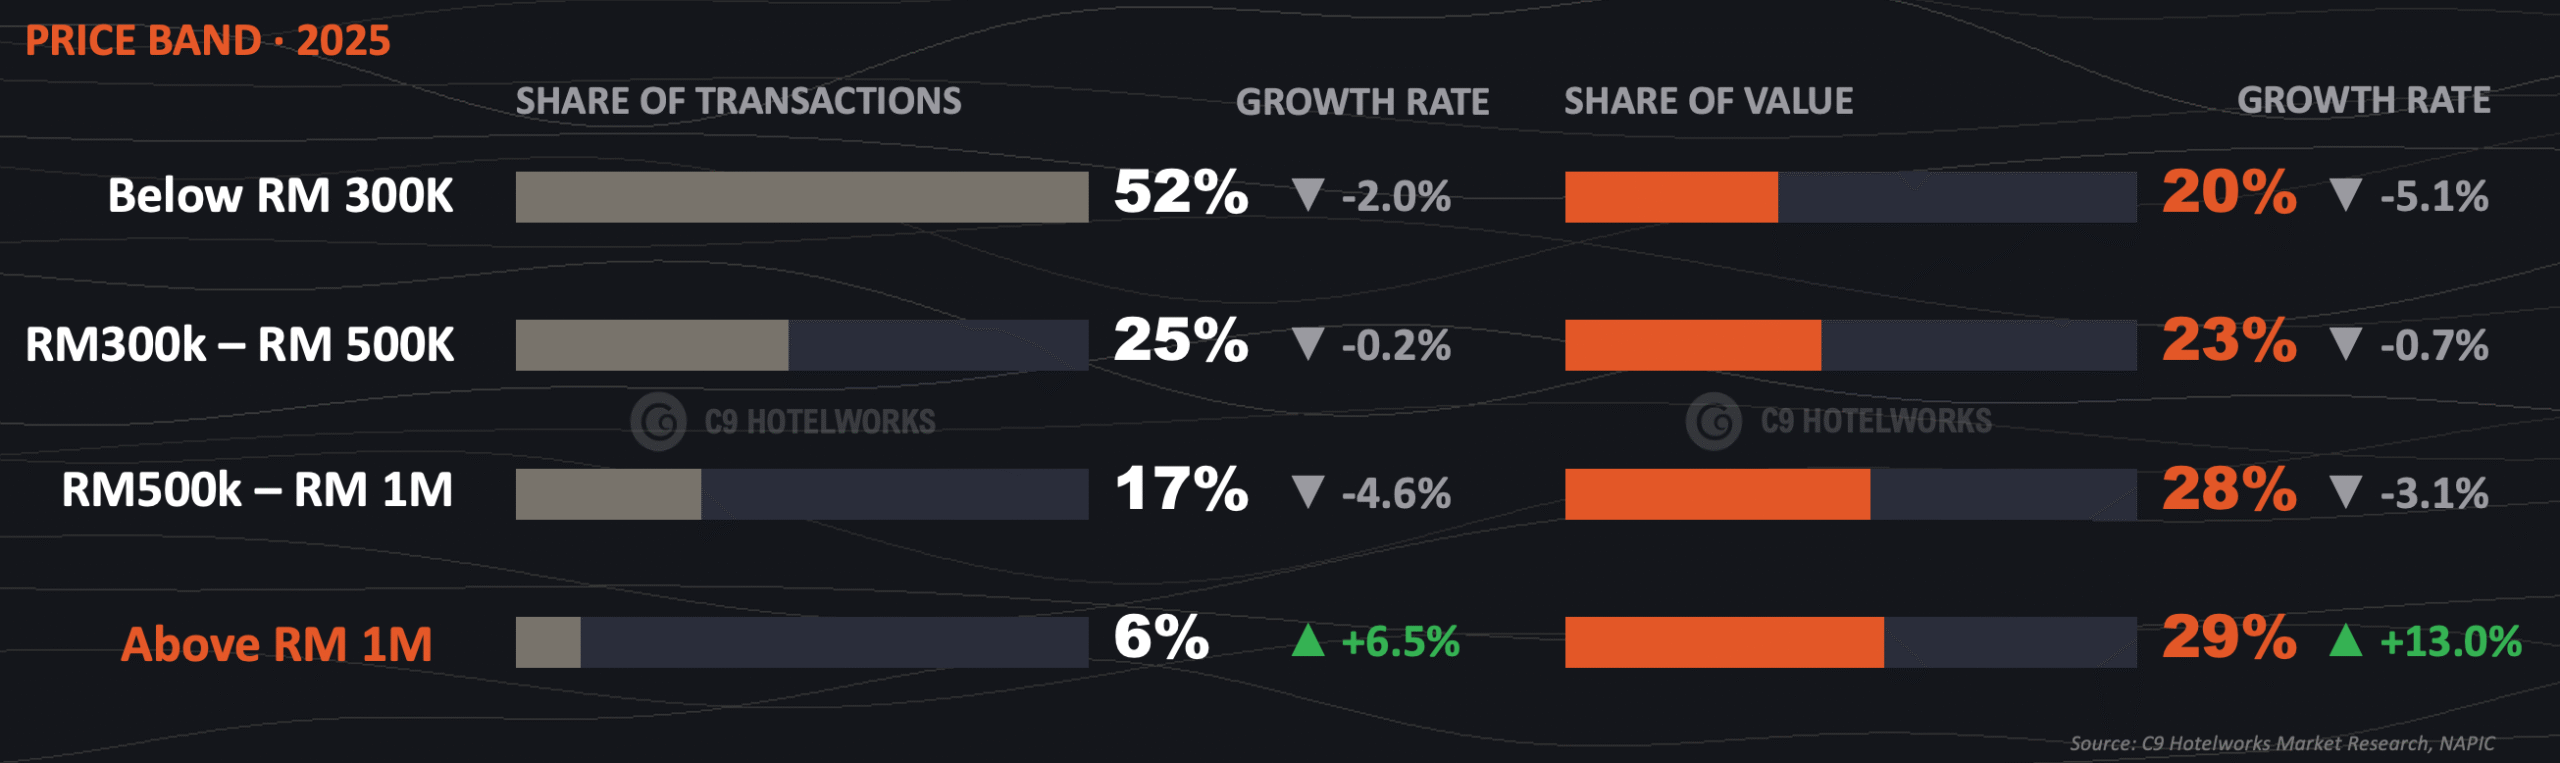
In the residential market, transaction value rose 1.3% year-on-year in 2025 even as transaction volume fell 1.5%, across 256,512 deals worth RM108.3 billion. Regional activity skews south, with Southern (Johor) at 28% and Central at 27% holding the two largest shares.
By price band, the RM1 million-plus band was the only band to grow, up 13% in value and 6.5% in volume, while every band below it contracted. Demand is concentrating in the tier where branded residences compete.
The Phuket International School Market Review 2026 analyses Phuket’s transition from a leisure destination to an international community. C9 Hotelworks research finds the sector will reach 18 international schools serving 5,075 students by August 2026, with a forecasted annual tuition value of THB2.5 billion (USD76.2 million).
Key Sections Covered
- Phuket International School Sector Expansion and Forecasted Annual Tuition
- Student Enrollment Growth
- International Source Market and Top International Nationalities
- Phuket’s GDP Contribution and Productivity Multiplier
- ED Guardian Visa and the Long Stay Family Residency Hub
- Strategic Advantages and Premium Infrastructure Pillars
- Bangtao / Cherngtalay: Phuket’s Leading International Lifestyle District
Investor Highlights
Phuket’s International School Sector Marks Its Transition from Leisure Destination to International Community
Phuket’s international school market has expanded 51% in three years and will reach 18 international schools by August 2026, with annual tuition forecasted at THB2.5 billion (USD76.2 million). It serves 5,075 students (2025/26) from more than 50 nationalities across global curricula. At Phuket’s three largest international schools (HeadStart, BISP, UWC Thailand), the foreign student mix is led by Russia (15%) and China (10%), followed by the UK and USA at 5% each.
Phuket performs at 2.2 times national productivity, accounting for 0.7% of Thailand’s population yet contributing 1.4% of national GDP. Six school openings or expansions between 2023 and 2026 represent significant capital commitments in a structurally resilient market.
The ED Guardian Visa grants one parent a renewable one-year residency per enrolled child, converting tourist families into long-stay residents. School enrollment locks in long-term housing demand from high-income families, directly feeding Phuket’s THB454.8 billion (USD14.1 billion) residential market.
Schools are also a precondition for foreign direct investment and the relocation of executives, joining branded residences, healthcare, and lifestyle retail as the four premium infrastructure pillars converging in Phuket. This convergence is most visible in Bangtao / Cherngtalay, Phuket’s leading international lifestyle district, which holds 54% of Phuket’s residences supply and 30% of the 2026–2030 hotel pipeline, and will add North London Collegiate School (NLCS), scheduled to open in 2028. International schools are a catalyst connecting people, capital, and opportunity for Phuket’s international community.
The Bangtao Effect analyses how Phuket’s Bangtao coastline is repositioning from a resort destination into an international coastal hub. C9 Hotelworks research finds nine hotels and nine branded residences from seven global brands will deliver 1,640 hotel keys and 1,649 branded residence units between 2026 and 2030, a near 1:1 ratio that adds one residence for every hotel key.
Key Sections Covered
- Bangtao Development Pipeline, 2026–2030
- Hotels and Branded Residences by Brand and Opening Year
- Brand Commitments
- Retail and Education Infrastructure
- Future Outlook and Insights
Investor Highlights
Bangtao Is Repositioning from Resort Coastline to Phuket’s International coastal Hub
Nine hotels and nine branded residences from seven global brands will deliver 1,640 hotel keys and 1,649 branded residence units in Bangtao between 2026 and 2030, alongside the POP Phuket mall and the North London Collegiate School (NLCS). At a near 1:1 ratio, the pipeline adds one residence for every hotel key.
The pipeline covers hotels, residences, retail and education, every component of a functioning international community. Bangtao is no longer drawing hotel groups alone: fashion (ETRO) and retail (Central Group) are expanding in the district.
The pipeline delivers across all five years from 2026 through 2030. The first openings come in 2026 with Mamaka, Standard Residences, and POP Phuket mall. Delivery peaks in 2028, when five projects including the NLCS campus open within a single year. IHG alone delivers 869 hotel keys by 2028, the largest commitment of any brand in the pipeline.
The planned Phase II expansion of Phuket International Airport adds capacity toward 2030, just as the Bangtao pipeline completes. North Bangtao Bay / Layan has two large-scale mixed-use developments combining hotels and branded residences, currently in early-stage development and underpinned by a sizable undeveloped land bank in the area.
#C9Hotelworks #C9Insider #Bangtao #Phuket #PhuketRealEstate #BrandedResidences #HotelInvestment #ThailandInvestment #MarketResearch
C9 Hotelworks presents the Batam & Bintan Hotel Residences Market Review 2026, providing an independent assessment of tourism demand dynamics, hotel residences performance, and destination investment insights across both Riau Islands markets. The report covers visitor arrivals trends, hotel performance, price indicators, and the evolving development landscape for hotel residences in Batam and Bintan.
Key Sections Covered in the Report
- Batam Tourism Market Overview
- Batam’s Hotel Residences Price Indicators
- Batam’s Hotel Residences Performance Indicators
- Bintan Tourism Market Overview
- Bintan’s Hotel Residences Price Indicators
- Bintan’s Hotel Residences Performance Indicators
Investor Highlights
1.Bintan’s Tourism Recovery Remains Domestically Driven
Bintan recorded 898,880 domestic and international visitors from January to November 2025, representing a Y-O-Y increase of 35% for the same period. International visitors rose by 17%, while domestic visitors grew by 42%. Despite positive momentum, Bintan’s international visitor recovery stands at just 38% of pre-pandemic levels, as the region’s tourism is largely driven by domestic demand.
Domestic visitor arrivals dominate Bintan’s tourism market in the Riau Islands, Indonesia, constituting 76% of market share, with 48% originating from Tanjungpinang and 34% from Batam. Among international visitors, Singapore leads at 49%, followed by Mainland China at 8% and Malaysia at 7%, reflecting Bintan’s strong appeal as a short staycation destination for regional tourists.

2.Bintan’s Hotel Supply Shifts Toward International Brands and Integrated Resorts
Bintan has a total of 24 properties and 2,946 keys belonging to star-rated hotels. Of the existing supply, 46% of room inventory is associated with international hotel chains, and 56% forms part of an integrated resort development incorporating mixed-use facilities such as shopping malls, parks, and golf courses.
Occupancy of star-rated hotels in Bintan declined to approximately 46% as of August 2025, largely due to rising average hotel room rates as new international branded hotels came onstream between 2022 and 2025. Improving rate performance for international branded hotels signals a market repositioning from budget to premium hospitality offerings.

3.Hotel Residences Supply Remains Stalled as Condominium-Type Hotel Managed Residences Dominate Inventory
Bintan has recorded a total of 1,685 hotel residences launched since the 2000s, with 78% of inventory belonging to condominium-type residences and the remainder comprising villa-type residences. A surge of condominium-type hotel residences launched during pre-pandemic has largely been on hold since, with current development yet to resume.
On the supply side, Bintan experienced exponential price growth which peaked around 2016 to 2019, creating a mismatch with its largely midscale buyer base. This supply and demand gap resulted in the collapse of several new projects that have yet to recover since COVID.

4.Condominium Prices Lead Villas on a Per-Square-Meter Basis as Singapore Buyers Drive Demand
As of 2025, the average sales price of condominium-type hotel residences in Bintan is IDR 42.7 million per Sq.m. (USD 2,670), with unit prices ranging from IDR 1 billion up to IDR 11 billion for penthouse units. Villas command a lower built-up sales price of IDR 36.2 million per Sq.m. (USD 2,263), though villa unit prices can reach up to IDR 22 billion.
International buyers are primarily from Singapore and Malaysia, while local buyers originate from nearby cities or Jakarta. Both buyer types cite investment as a key driver of purchase, whereby rental income or capital gains are key deciding factors. Studio and one-bedroom units are the most preferred configuration for condominium-type hotel residences, while two-bedroom villas are favored for villa-type residences catering to small families.

5.Design-Led Resort Development Is Redefining Bintan’s Hospitality Identity
While Bintan’s hotel residences market faces stagnation from outdated products, the area’s overall hotel performance — particularly international branded hotels — is improving as the market welcomes new supply with more creative design concepts compared to traditional full-service resorts. Tourism trends in Bintan have shifted from standard resorts toward design-led, selected-service developments focused on unique staycation experiences for domestic visitors.
Despite Batam and Bintan sharing close proximity and similar demand profiles, the development directions required for both destinations to work in tandem are very different — and unlocking this distinction will be key to activating new potential in both Indonesia island markets.
#BintanBrandedResidences #BintanTourism #IndonesiaBrandedResidence #IndonesiaHotelInvestment #RiauIslands #BrandedResidences #MarketResearch #HotelInvestment #C9Hotelworks #C9Insider
C9 Hotelworks presents the Asia Branded Residences Market Review 2026, providing an independent assessment of Asia’s branded residences sector across across Vietnam, Thailand, South Korea, India, the Philippines, Japan, Singapore, Malaysia, the Maldives, Indonesia, China, Taiwan, Sri Lanka, and Cambodia, covering regional supply dynamics, market valuation, standalone branded residences trends, operational model shifts, and the development outlook for hospitality-led real estate.
Key Sections Covered in the Report
- Asia Branded Residences Market Overview and Valuation 2026
- Branded Residences Supply by Country, Chain scale, and Product Type
- Standalone Branded Residences and Non-Hospitality Brand Growth
- Secondary Markets, Hybrid Developments, and Drive-to Destination Growth
- Branded Residences Operations and Rental Management Programs
Investor Highlights
1. Asia’s Branded Residences Market Value of USD40 Billion Is Led by Vietnam, Thailand, and South Korea
In 2026, the pipeline of branded residences in Asia available for sale is valued at USD40 billion across 50,025 units, with 18,545 units scheduled for completion from 2026 through 2028. This market value reflects a significant 30.3% year-on-year increase for Asia’s branded residences sector. Such growth is underpinned by a total supply of 64,581 units across 268 developments, an inventory that includes 14,556 unlaunched units.
Vietnam and Thailand are leading markets by value, with Vietnam’s market valuation approaching USD8 billion. This concentration aligns with a 2026 delivery peak of 7,818 units across 39 projects, marking a recovery from the 2022 supply low. Collectively, these markets continue to drive regional value growth.


2. Luxury Dominates Value While Resort Destinations Outpace Urban Supply
The luxury segment accounts for 56% of total market value, followed by the upper upscale (14%) and non-hospitality & independent (13%) segments as primary contributors. Condominiums remain the dominant asset class at 94% of supply (60,511 units), with landed properties (4%) and hybrid formats (2%) occupying niche positions in the regional market.
Resort based assets represent 55% of supply, indicating a concentration in leisure oriented locations over urban destinations. Luxury development continues to dominate the region’s leading markets, with Thailand leading in scale with 30 luxury developments, while Vietnam and South Korea follow with 18 and 13 projects respectively. These markets account for 50% of total market value, highlighting the outsized contribution of luxury developments to regional value.


3. Standalone branded Residences and Non-Hospitality Brands Are Accelerating Market Expansion
The standalone model now accounts for 17% of Asia’s branded residences supply, representing an increase of approximately 3,300 units. The share of standalone projects completing from 2025 onwards reached 19%, up from 13% previously. This trend reflects a declining reliance on co-located hotel models, particularly in mature markets such as Japan and India. Furthermore, development scale varies by market, with Manila leading in volume with 1,683 units across three projects, reflecting a high density urban approach, while Phuket comprises 678 units across eight projects, indicating a preference for lower-density boutique resort developments.
While hotel groups account for 81% of the standalone market, non-hospitality brands are emerging as key growth drivers. Representing 19% of units, the segment is led by design (59%) and fashion (40%) brands such as YOO and Elie Saab, leveraging standalone models to grow through strong brand identity. The model is also transitioning from urban concentration (84% share pre 2025) toward resort destinations, which account for 61% of the upcoming pipeline. This growth reflects a broader application of the standalone concept across both condominium and landed property projects.


4. Secondary Destinations and Hybrid Models Are Decentralizing the Sector
As familiarity with the branded residences model increases, developers are expanding into drive-to destinations within three hours of major cities. Locations such as Hua Hin (3,017 units), Phan Thiet (788 units), and Sokcho (717 units) provide branded residences at more accessible price levels than primary hubs. These markets capture demand from weekend-getaway users and regional investors as alternatives to primary hubs such as Bangkok, Ho Chi Minh City, and Seoul.
Hybrid developments (1,229 units) are concentrated exclusively in resort destinations with no urban presence. Indonesia leads this segment with a 34% hybrid share, leveraging a mix of condominium units and landed properties to capture diverse buyer segments. This model enables developers to optimize absorption by targeting multiple demand profiles within a single project.


5. Operational Models Are Shifting from Mandatory Yields to Flexible Ownership Programs
Rental management participation has transitioned from a mandatory requirement to an optional program across the region. Under the previous model, purchases were positioned as yield driven investments with projected returns, exposing developers to regulatory and legal risks when projections were not met. Developers now favor optional participation models to mitigate financial risk in mature markets, with the focus shifting toward asset value and long term capital preservation.
Revenue distribution is structured under two allocation models: rental pooling, which aggregates income and distributes returns on a standardized per square meter basis, and individual allocation, which distributes based on actual unit performance. In markets such as Thailand and the Philippines, this shift empowers owners with lifestyle flexibility but increases operational complexity for managers navigating fluctuating inventory and more intricate revenue sharing structures.

#C9Hotelworks #C9Insider #BrandedResidences #AsiaRealEstate #HotelInvestment #Hospitality #MarketResearch #AsiaPacific #LuxuryResidences #RealEstateInvestment
C9 Hotelworks presents the Vietnam Branded Residences Market Update 2026, providing an independent assessment of Vietnam’s branded residences sector, including construction cost dynamics, tourism demand, supply pipeline, pricing benchmarks, demand segmentation, ownership structures, and the forward outlook for hospitality-led real estate market.
Investor Highlights
1. Rising Costs and Rate Pressure Are Reshaping Development Strategy
Vietnam’s national construction price index reached 119 in 2025 (base year 2020 = 100), reflecting sustained cost escalation across key building inputs. This rise in development costs has influenced developers to reconsider project structures and delivery models to maintain long-term feasibility.
International tourist arrivals recovered to 21.2 million in 2025, a 20% year-on-year increase. However, accommodation and food services revenue growth remained nearly flat compared to 2019, signaling ongoing rate pressure for pure hotel developments. Together, rising construction costs and volatile hotel cash flows are driving a structural shift toward hybrid assets developments that combine hotel operations with branded residences components to diversify revenue streams and accelerate capital recovery.

2. Vietnam Leads Asia’s Branded Residences Market by Value
Vietnam’s branded residences market value has reached USD8.0 billion, representing 20% of the total USD40.0 billion Asia branded residences pipeline. The market recorded a 30% year-on-year increase in value, making it the largest branded residences market in Asia by aggregate sales value, ahead of Thailand (USD6.4 billion), South Korea (USD5.8 billion), India (USD4.2 billion), and the Philippines (USD3.8 billion).
Current supply stands at approximately 15,763 units, with condominiums comprising 93% (14,615 units) and landed or hybrid properties accounting for 7% (1,148 units). In terms of geographic distribution, Central Vietnam accounts for 55% of market activity, led by resort destinations including Danang (2,659 units), followed by the South, anchored by Ho Chi Minh City (1,818 units), and the North, centered on Hanoi (1,817 units).


3. Price Competitiveness Across Urban and Resort Markets
Branded residences average sale prices per square meter in Vietnam remain 24–39% below Bangkok in urban destinations and up to 63% below Phuket and Bali in resort destinations reinforcing Vietnam’s position as one of Asia’s most price-competitive branded residences markets.
Branded residences in Vietnam command a price premium of 20–55% above conventional residential products in urban markets and 10–35% in resort locations, reflecting the value attributed to hotel brand affiliation, professional management, and shared amenities.

4. Demand Segmentation and Rental Management
Demand characteristics demonstrate a clear divergence between urban and resort sectors. In urban locations, demand consists of both investment buyers (approximately 70%) and end-users (30%), with domestic purchasers forming the majority. In contrast, the resort market is primarily investment-driven (approximately 80%), where buyers frequently participate in hotel-managed rental programs with only a small proportion using units for personal stays.
Guaranteed returns, once a key selling point for branded residences, have steadily declined with some hospitality-led offerings now carrying no guaranteed return at all. In its place, structured and professionally managed rental programs are increasingly becoming a market expectation rather than a differentiator.


5. Ownership Structure and Foreign Buyer Framework
Ownership regulations in Vietnam differentiate between foreign and domestic participants. Foreign buyers are restricted to a 30% quota of condominium units within a single building and a maximum of 250 landed units per ward. Ownership for this segment is structured as leasehold tenure of up to 50 years with potential for extension. Domestic buyers hold long-term land use rights, where the state retains land ownership while granting permanent residential usage rights to individuals functioning similarly to freehold ownership in market practice.
Foreign demand is present but structurally capped by tenure limits, ownership quotas, and product classification requirements. As a result, Vietnam’s branded residences market remains primarily driven by domestic buyer absorption.
6. Future Outlook
Vietnam’s branded residences market has expanded alongside the recovery of international tourism and the adjustment of development structures in response to rising costs. Key trends shaping the sector’s trajectory include the shift toward investment-driven demand with stronger brand credibility requirements, the institutionalization of rental management programs, and infrastructure-led value growth driven by major projects such as the Hanoi–Ho Chi Minh City high-speed rail and Long Thanh International Airport. Looking ahead, long-term asset value will depend on management transparency, operational consistency, and the sustainability of revenue-sharing models.
Key Sections Covered in the Report
- Vietnam Overview
- Market Insights and Regional Positioning
- Price Competitiveness: Vietnam vs Bangkok & Bali
- Demand Segmentation and Rental Management
- Ownership Structure and Foreign Buyer Framework
- Future Outlook
#VietnamBrandedResidences #VietnamRealEstate #VietnamTourism #BrandedResidences #HotelInvestment #AsiaPacific
Bali’s real estate market has over seventy hospitality-managed real estate developments actively on sale. Development activity remains heavily concentrated in the Canggu/Berawa area, which accounts for approximately 40% of total supply. Uluwatu represents the second-largest hub at 21%. However, escalating land constraints and rising density in Canggu/Berawa are driving new development toward the northwest coastline, including Seseh, Pererenan, and Nyanyi. This emerging northwest coastline cluster now represents approximately 17% of total supply, including the Nuanu City mixed-use development, which comprises eleven residential projects in the primary market as of February 2026.
The current inventory is characterized by a high concentration of boutique-scale projects. Villa inventory accounts for approximately 18% of total supply, up from 13% in the previous year, reflecting a surge in new villa project launches. The majority of these developments remain small in scale, with approximately 84% comprising fewer than thirty villas.

Ownership Structure
Leasehold structures continue to dominate the market, typically ranging between 25 and 35 years, generally with renewal provisions subject to agreement. These structures have historically catered to foreign investor demand seeking entry-level exposure to Bali’s resort property market.
Notably, ownership structures offered by developers are shifting. Freehold offerings have increased from
12% of total supply in 2025 to approximately 23% in 2026, driven primarily by new project launches in Seseh, Pererenan, and Nyanyi. In contrast, properties in Canggu and Berawa remain predominantly leasehold, while other regions of Bali typically exhibit higher concentrations of freehold inventory, ranging between 36% and 50%.
The expansion of freehold supply is expected to attract a broader segment of domestic Indonesian buyers.

Key Issue
As the historical dominance of small-scale developments has resulted in regulatory gaps, the provincial government is now strengthening its oversight of the real estate rental market. This transition is primarily driven by a mandate requiring all short-term rental accommodations to demonstrate full legal compliance by March 31, 2026. Properties listed on online travel agencies (OTAs) that fail to verify their business registration through the national digital framework face systematic removal from major booking platforms. Rather than imposing restrictions on rental platforms — such as banning certain platforms — this enforcement ensures tax compliance, standardizes safety protocols, and restores competitive parity between traditional hotels and unregistered short-term rentals.
Under the 2026 framework, the barrier to entry for independent foreign investors has increased due to legal restrictions that prevent foreign individuals from directly holding the tourism-specific operating licenses required for short-term rentals. This requirement creates a bottleneck for international buyers, as foreign investors must either establish a PT PMA (Perseroan Terbatas Penanaman Modal Asing – Foreign Investment Company) or rely on the underlying local landowner for legal compliance. Opting for a PT PMA structure entails operational complexity, increased management costs, and a minimum investment of IDR 10 billion.
Outlook
With the pressure from the heightened requirements, a shift in foreign investor demand is projected toward branded residences, which currently account for approximately 10% of the total active supply. Typically integrated within hotel or mixed-use developments, these branded residences offer professionally and legally managed rental structures that provide a transparent investment opportunities alternative to the unregulated, small-scale market. Notably, Raffles Residences Bali is expected to launch in the second quarter of 2026, which will introduce 28 oceanfront villas with unit sizes starting from 502 square meters.
C9 Hotelworks forecasts an increase in resale activity of unlicensed rental villas, with tourists shifting toward traditional hotel accommodations. Looking ahead, co-located hotels and branded residences are expected to emerge to capture this transition.
Key Sections Covered in the Report
- Hotel & Tourism Market
- Tourism Market Overview
- Hotel Market Performance
- New Supply
- Real Estate Market
- Market Overview
- Ownership Structure
- Key Issue
- Outlook
#BaliRealestateMarket #BaliBrandedResidences #BaliPropertymarket #C9Insider #C9Hotelworks