Vietnam Branded Residences Market Review 2026/2027
Market reports
TO DISCUSS YOUR PROJECT OR LEARN MORE ABOUT OUR SERVICES:
Category: Branded Residences | Tourism
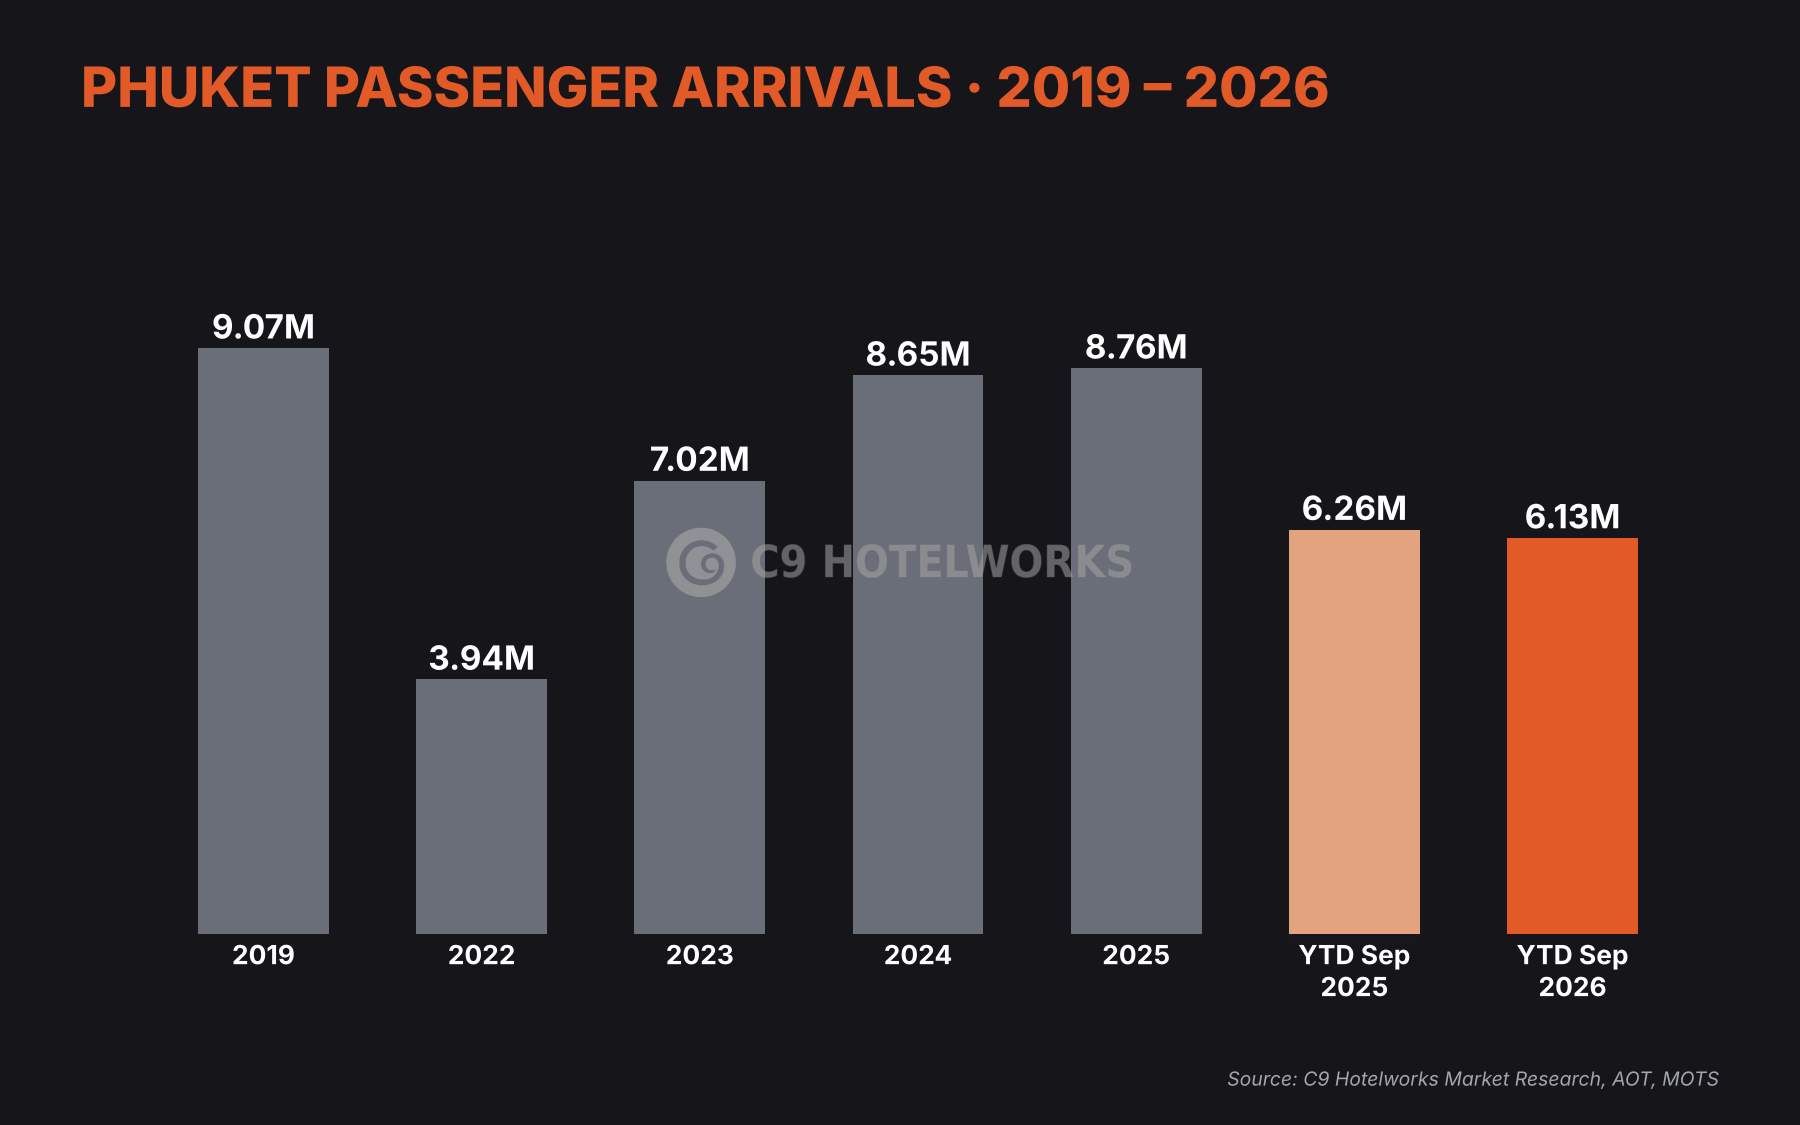
Phuket International Airport recorded 6.13 million passenger arrivals from January to September 2026, down 2% year-on-year, while tourism revenue fell 1% to THB400 billion. The report covers tourism performance, hotel occupancy and ADR, a 5,517-key hotel pipeline, 45,027 residential units for sale, branded residences supply and key infrastructure developments. Bangtao and Cherngtalay account for 22% of hotel pipeline keys, 39% of residential supply and 50% of branded residences units.
1. China Leads Source Market Growth as Phuket Passenger Arrivals Fall 2%
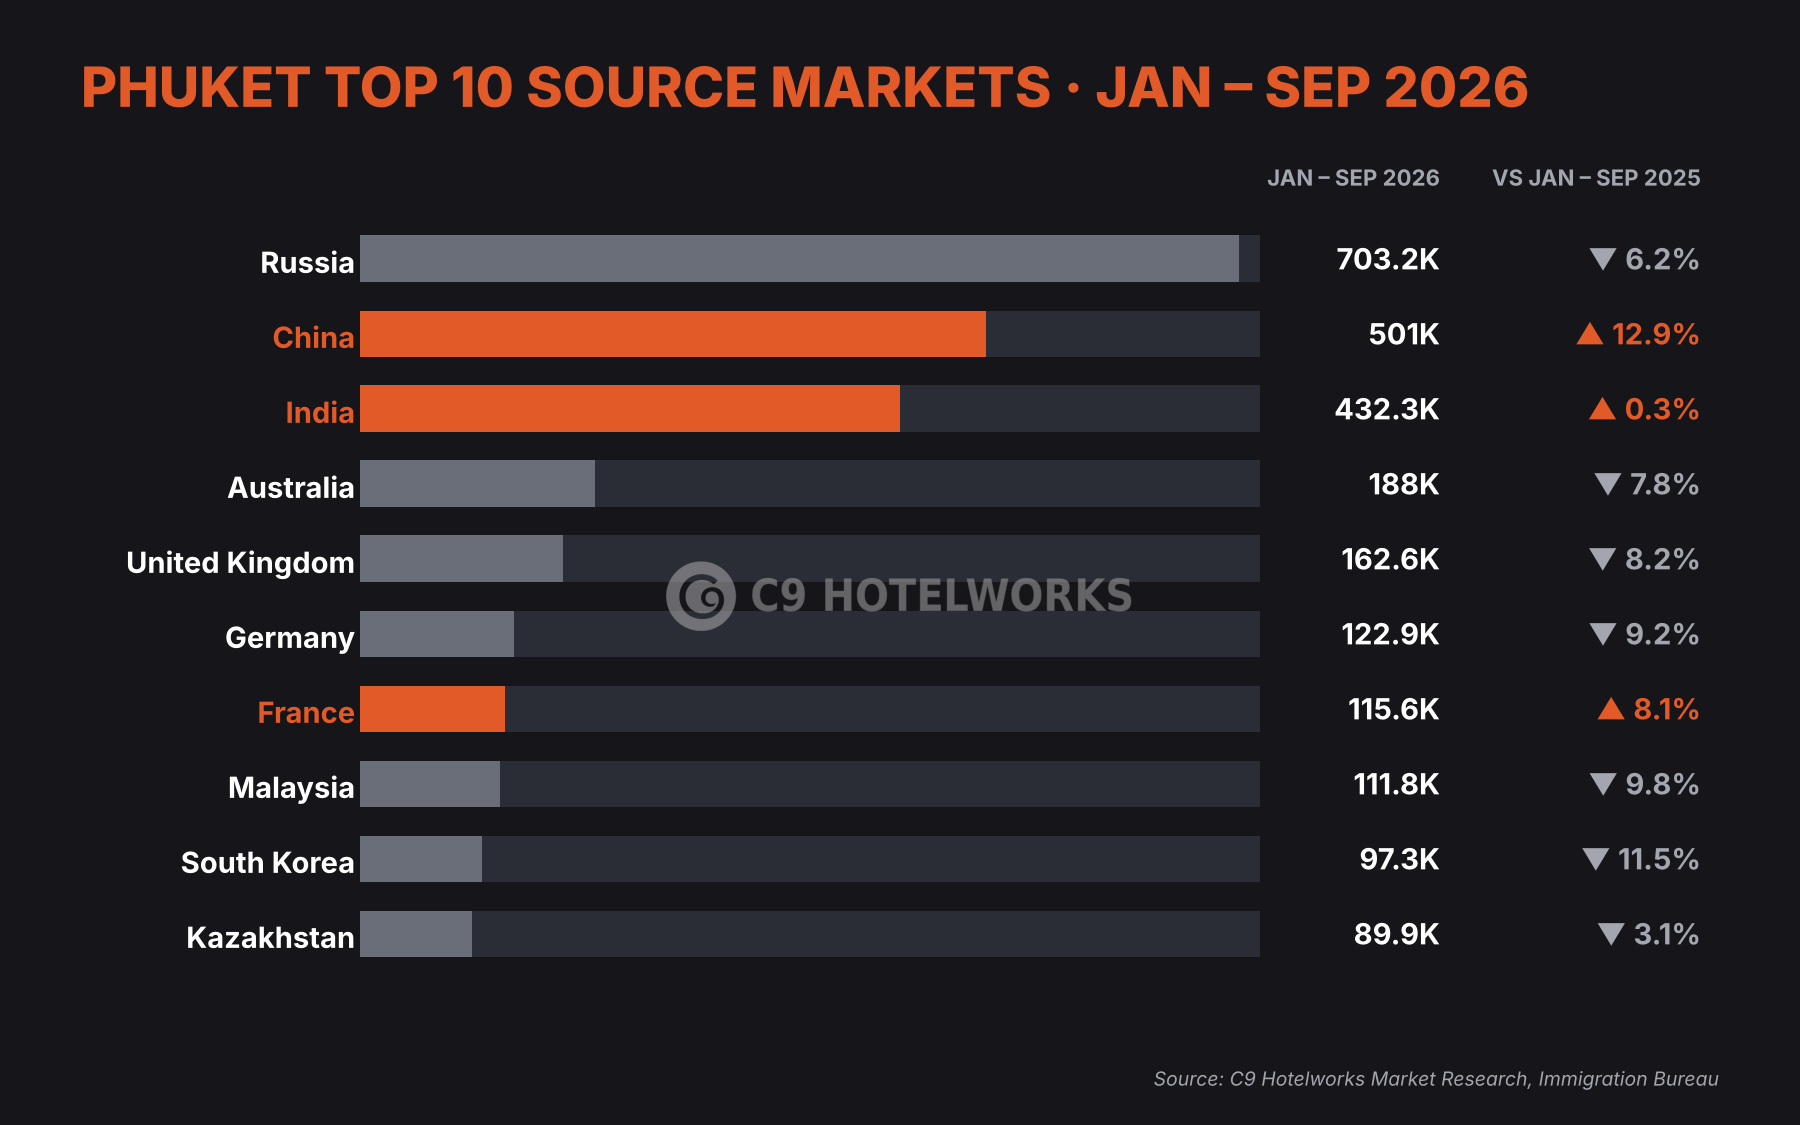
Phuket International Airport recorded 6.13 million passenger arrivals from January to September 2026, down 2% from 6.26 million a year earlier. International passengers accounted for 62% (3.80 million), while domestic passengers made up 38% (2.33 million). Tourism revenue reached THB400 billion, down 1% from THB404 billion, with international visitors contributing 92% of the total.
China recorded the largest increase among the top 10 international markets, up 12.9% to 501,000 passenger arrivals. Only three markets recorded growth: China, France (up 8.1%) and India (up 0.3%). Russia remained the largest source market at 703,200 arrivals, down 6.2%. South Korea and Malaysia recorded declines of 11.5% and 9.8%, respectively.
2. Phuket Hotel ADR Down 4.1%, but Above 2025 Levels Throughout the Third Quarter
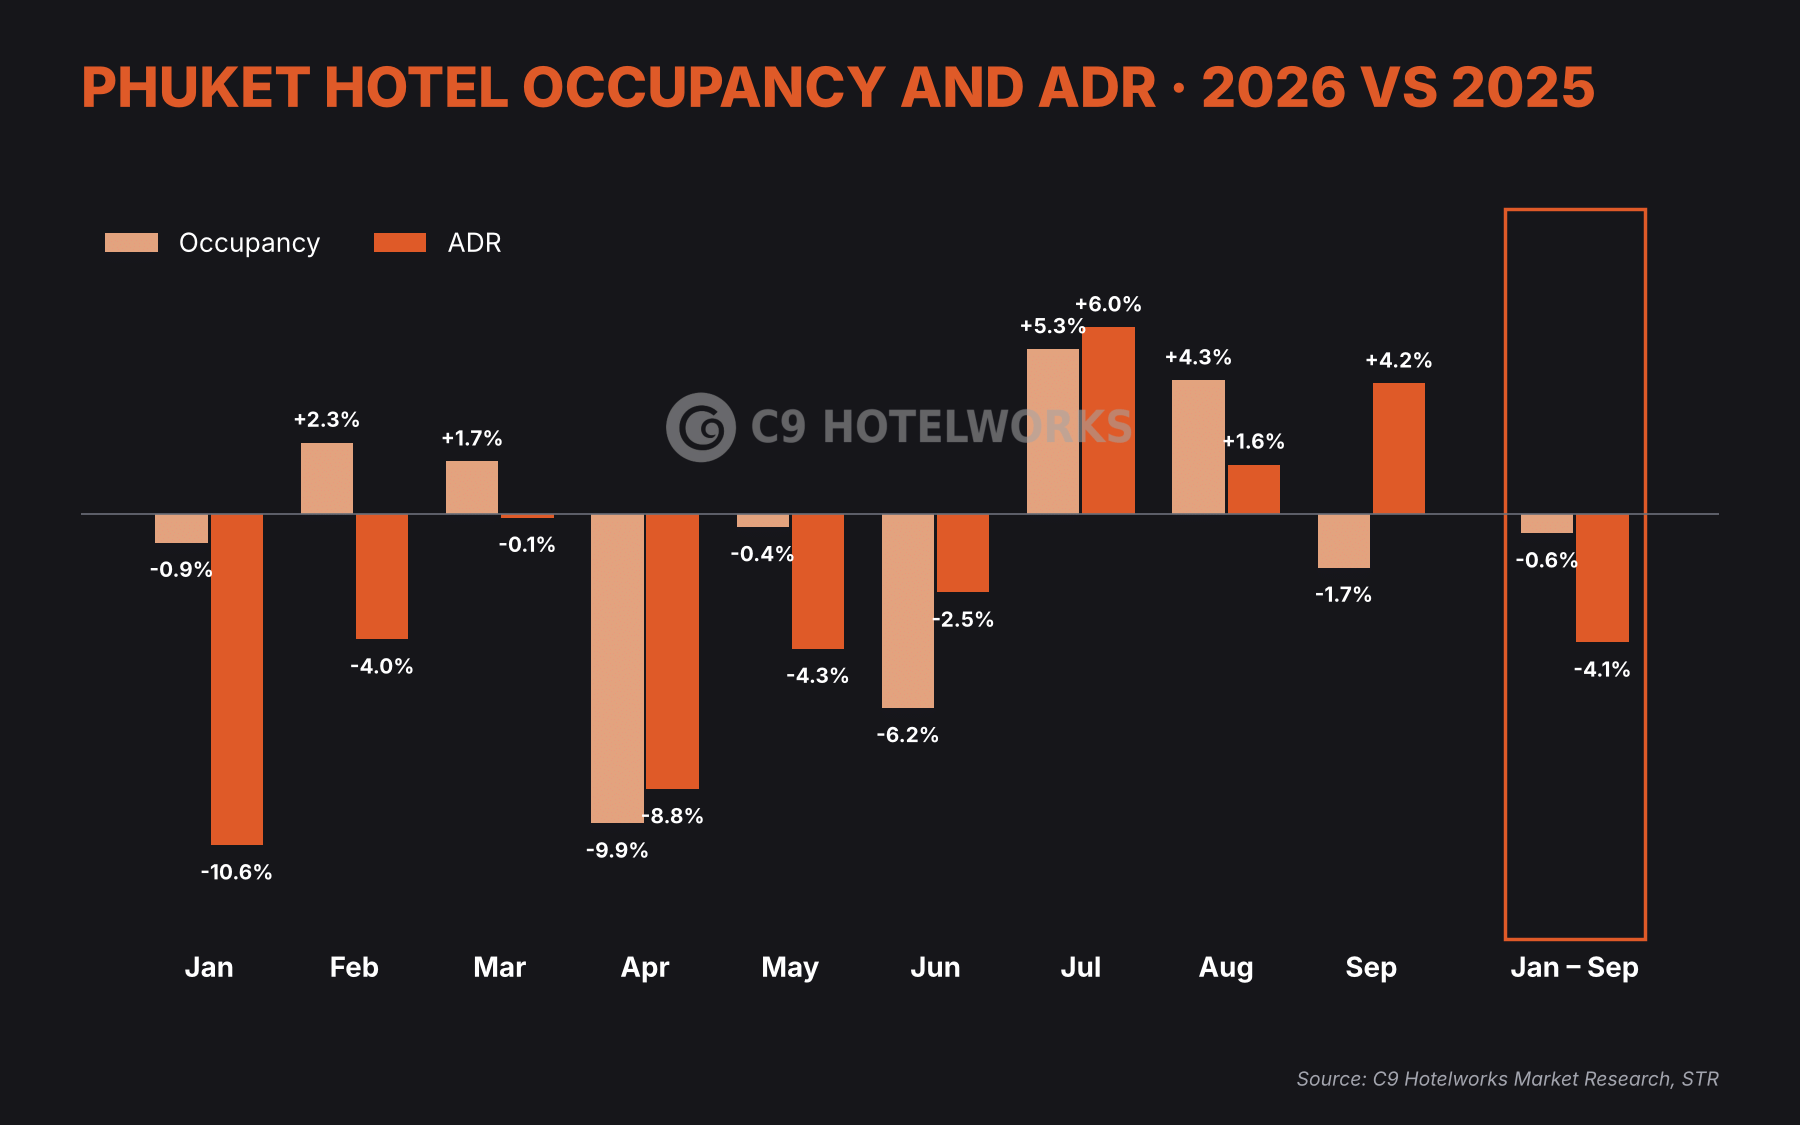
Phuket hotel ADR fell 4.1% year-on-year from January to September 2026, while occupancy remained broadly flat, down 0.6%. April recorded the largest monthly declines, with occupancy down 9.9% and ADR down 8.8%. January recorded the steepest ADR decline, at 10.6%.
ADR was above 2025 levels in each month from July to September, increasing 6.0% in July, 1.6% in August and 4.2% in September. Occupancy recorded its strongest growth in July, up 5.3%, followed by 4.3% in August, before declining 1.7% in September.
3. Phuket Hotel Pipeline Totals 5,517 Keys, with 2,192 Scheduled for 2027
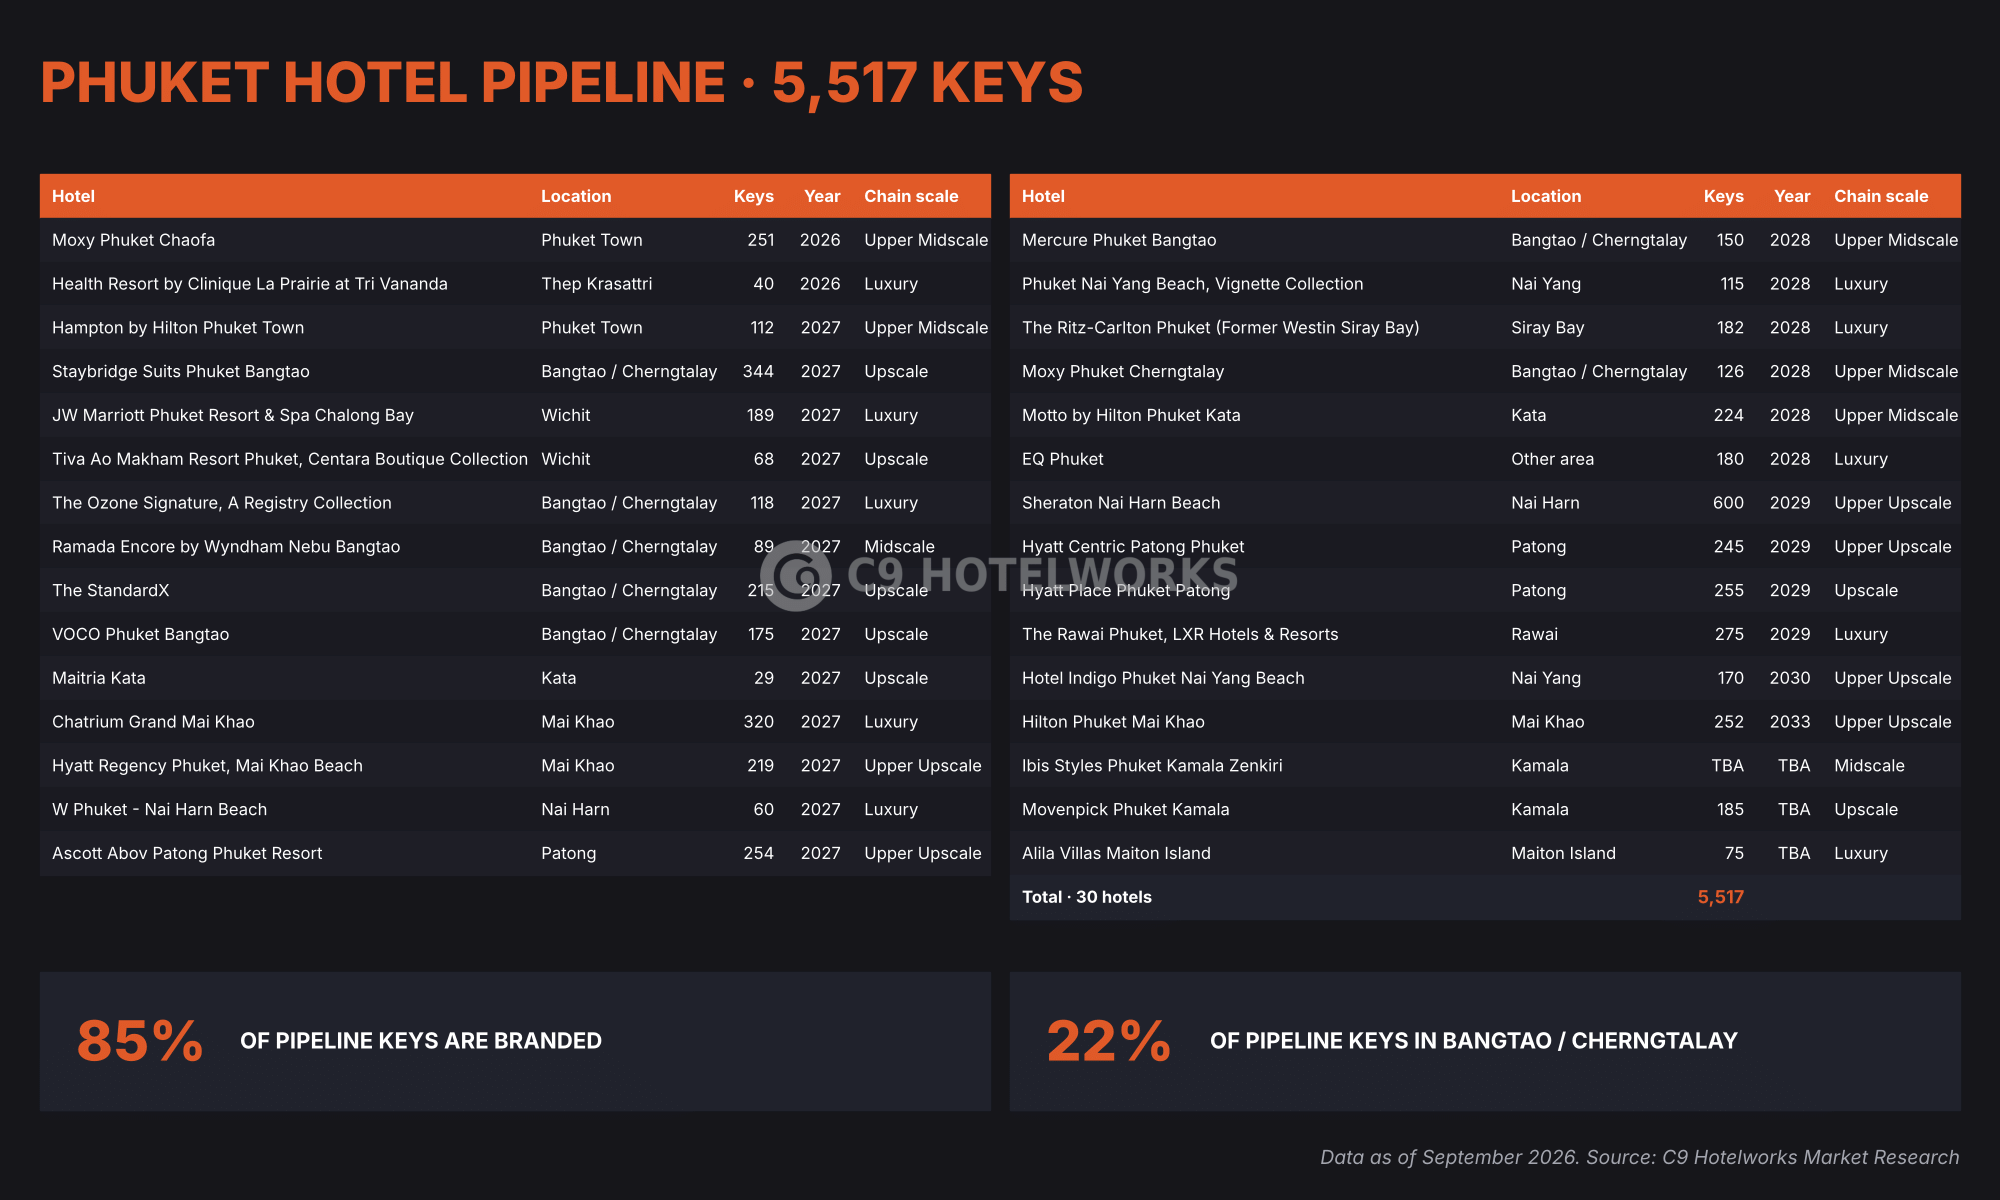
Phuket’s hotel pipeline comprised 30 hotels and 5,517 keys as of September 2026, with branded hotels accounting for 85% of pipeline keys. 2027 is the largest scheduled opening year, with 13 hotels and 2,192 keys, representing 40% of the pipeline. These include Staybridge Suites Phuket Bangtao (344 keys), Chatrium Grand Mai Khao (320 keys) and Ascott Abov Patong Phuket Resort (254 keys).
Bangtao and Cherngtalay account for 22% of pipeline keys across seven hotels, the largest share among Phuket’s areas. Projects include The Ozone Signature, A Registry Collection and voco Phuket Bangtao. The largest individual project is Sheraton Nai Harn Beach, with 600 keys scheduled for 2029. Luxury hotels account for 1,554 keys, or 28% of the pipeline, including The Rawai Phuket, LXR Hotels & Resorts.
4. Bangtao and Cherngtalay Account for 39% of Phuket’s 45,027 Residential Units for Sale
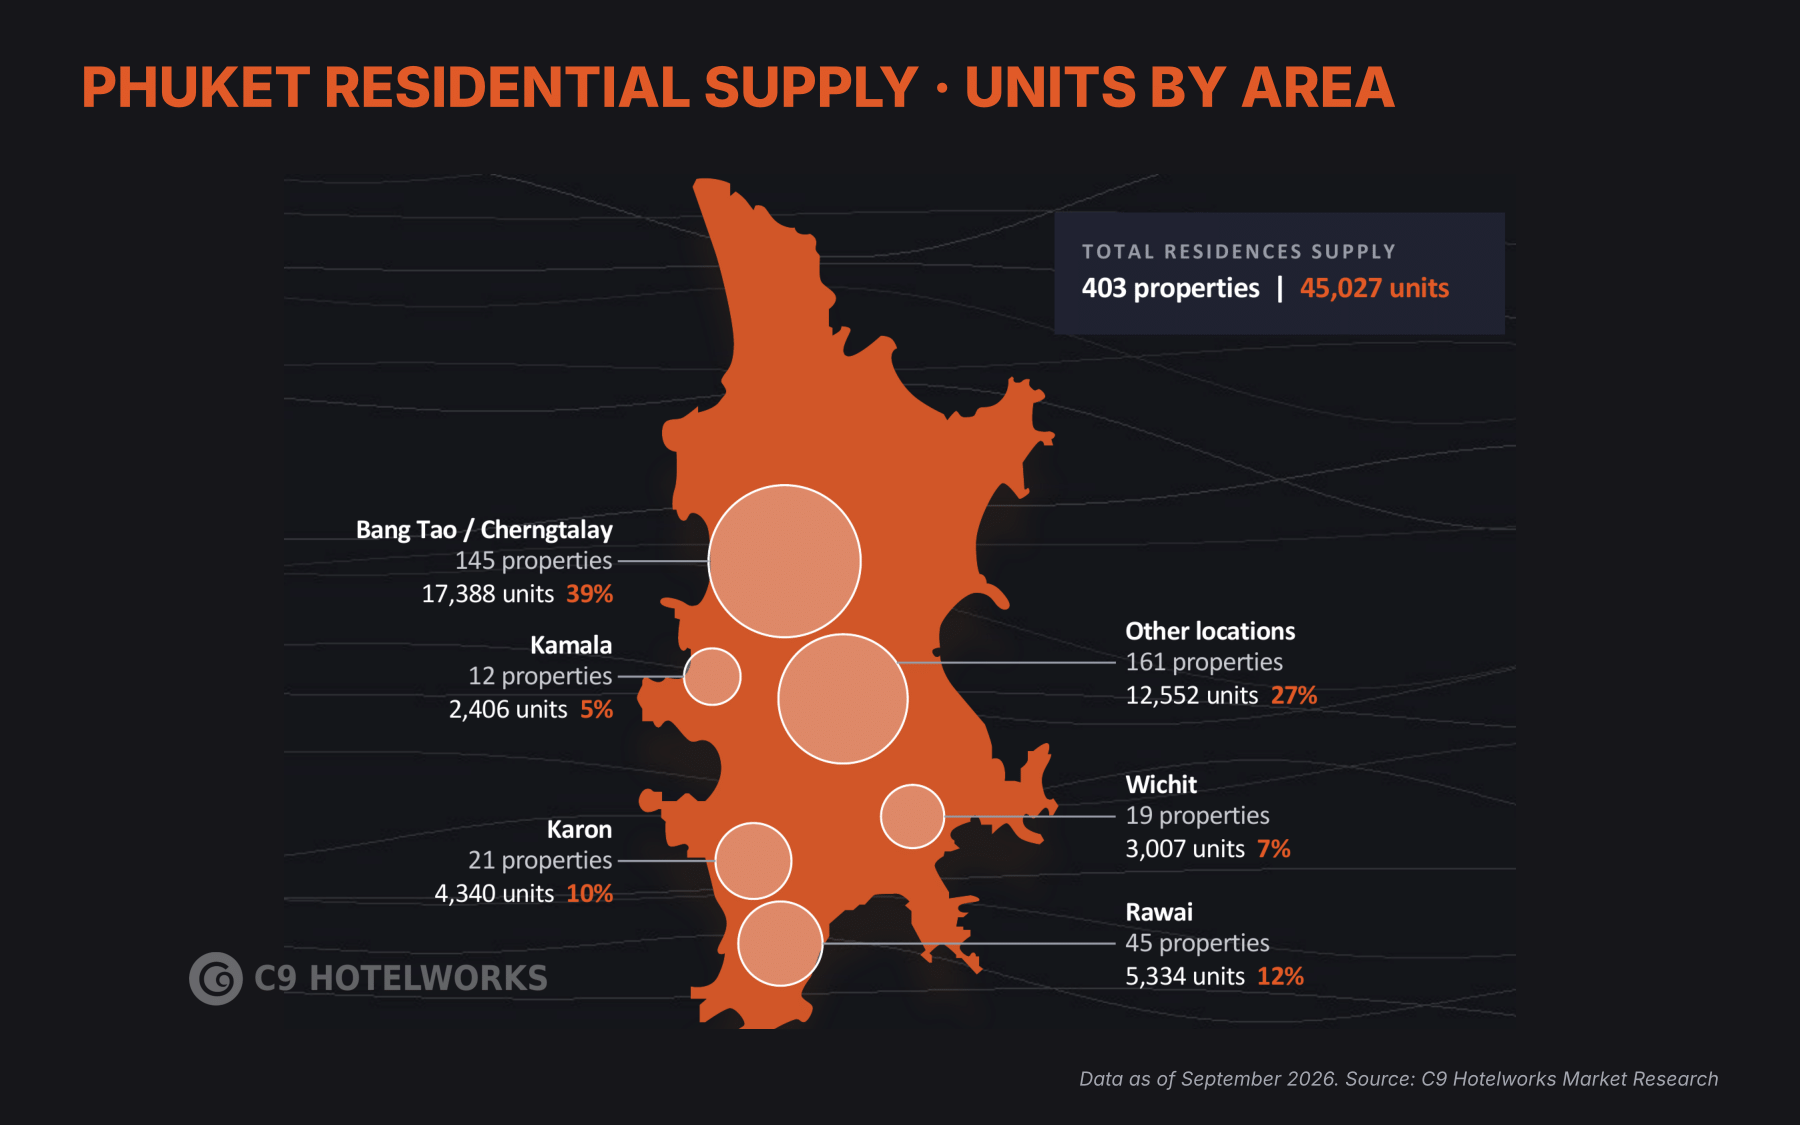
Phuket had 403 residential properties comprising 45,027 units for sale as of September 2026. Bangtao and Cherngtalay lead with 145 properties and 17,388 units, accounting for 39% of supply. Rawai follows with 5,334 units (12%), followed by Karon (4,340 units, 10%), Wichit (3,007 units, 7%) and Kamala (2,406 units, 5%).
Condominiums account for 83% of units, with landed property making up the remaining 17%. Branded residences represent 11% of total supply, while non-branded properties account for 89%. Bangtao and Cherngtalay have the largest supply of both branded and non-branded units among Phuket’s areas.
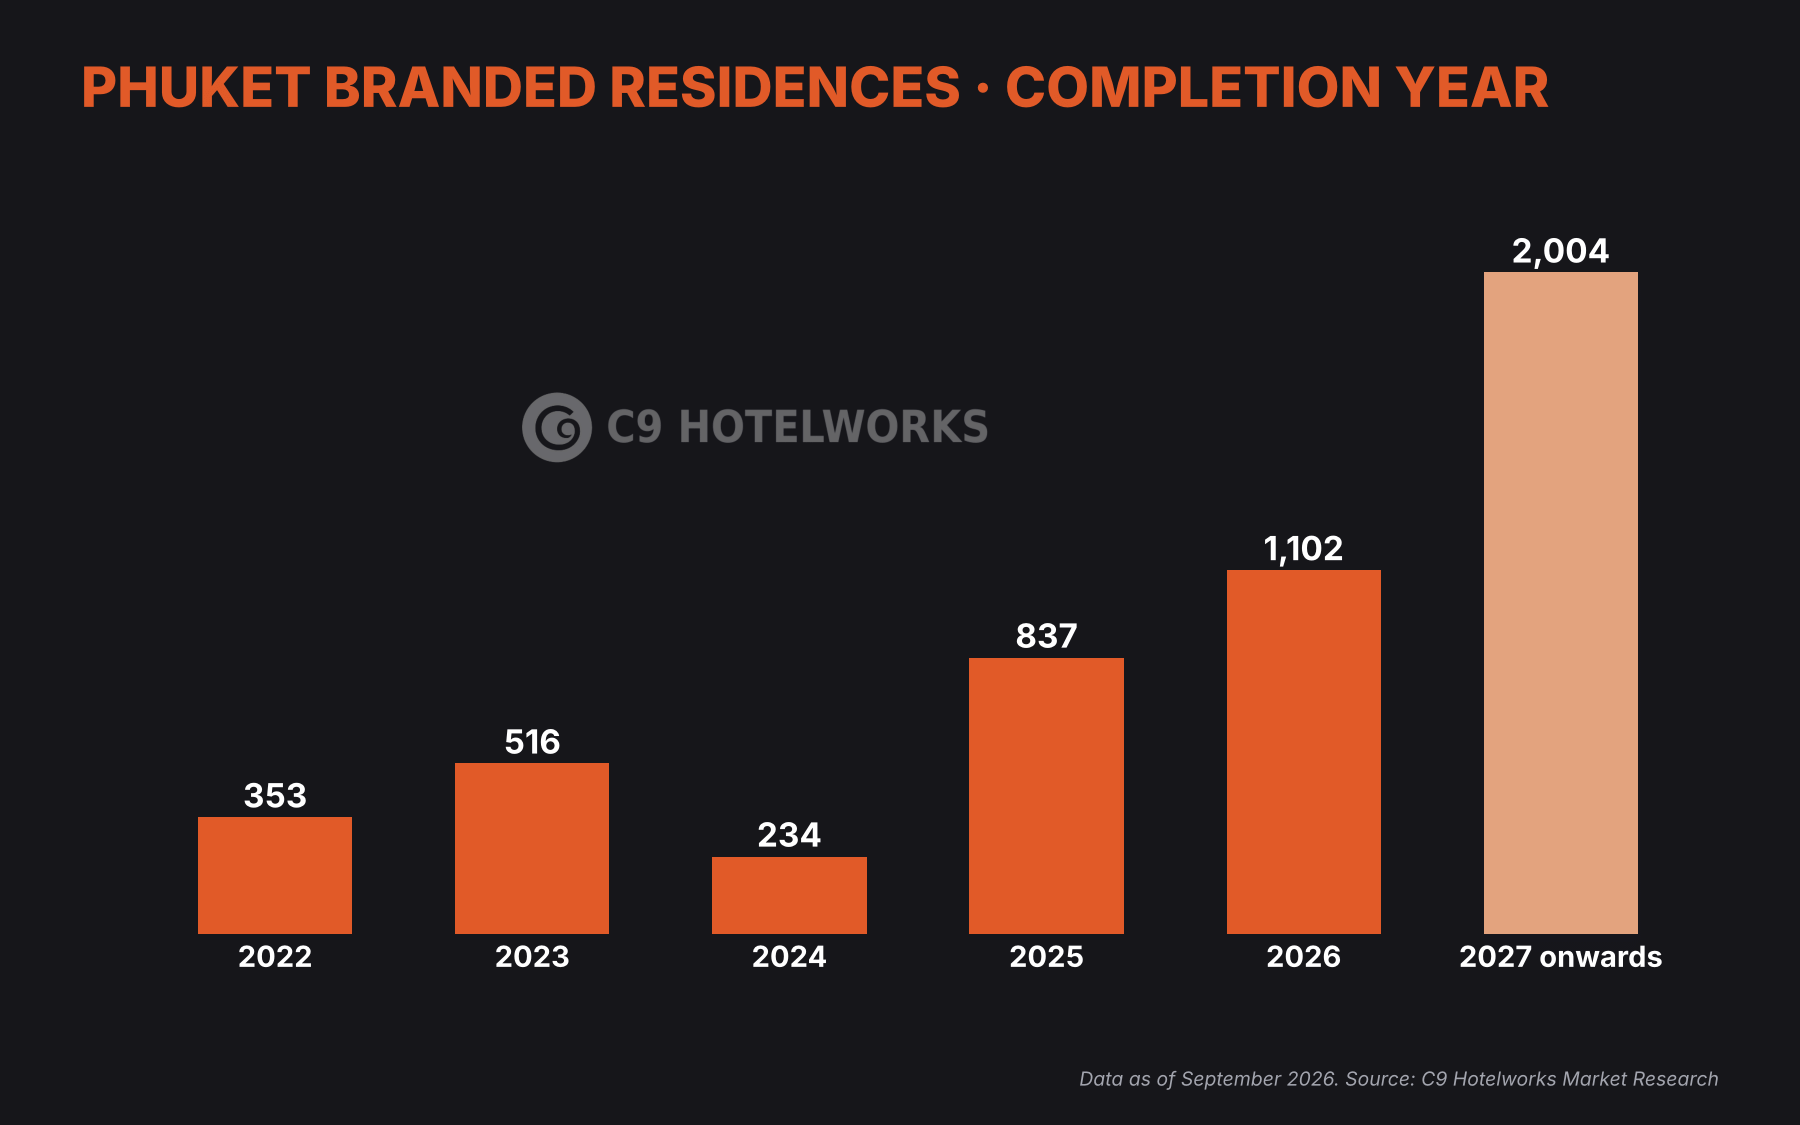
5. Phuket Branded Residences Completions Reach 1,102 Units in 2026, with 2,004 More Due from 2027
Phuket’s branded residences in the primary market and pipeline total 5,046 units. Annual completions increased from 234 units in 2024 to 837 in 2025 and 1,102 in 2026, the highest annual total over the 2022–2026 period. A further 2,004 units, representing 40% of total supply, are scheduled for completion from 2027 onwards.
Branded residences are more concentrated in certain areas than the wider residential market. Bangtao and Cherngtalay account for 50% of branded residences units, compared with 39% of all residential units for sale. Rawai follows with 20%, Kamala with 15%, Chalong with 8% and Patong with 4%. Kamala’s share of branded residences (15%) is notably higher than its share of total residential supply (5%).
6. Phuket Airport Expansion Targets 44% More Capacity by 2030
Phuket International Airport Phase II is planned to increase annual passenger capacity from 12.5 million to 18 million by 2030, a 44% increase, with an estimated investment of THB6.2 billion. The project is awaiting Cabinet approval. Andaman International Airport in Phang Nga is planned to handle 20 million passengers annually in Phase I by 2037, with an estimated investment of THB80 billion. Capacity is expected to reach 40 million passengers following Phase III. The project is at the feasibility study and Environmental Impact Assessment (EIA) stages.
Two road projects are targeted for completion in 2031. The Kathu–Patong Tunnel (3.98 km, THB16.8 billion) is scheduled for Cabinet consideration in December 2026. Phuket Expressway Phase 2 (30.6 km, THB46.8 billion) has received EIA approval. The draft Phuket Town Plan, expected in 2027, proposes increasing height limits in designated red zones from 23 metres to 45–60 metres (approximately 15–20 storeys) in Patong and parts of Thalang, Phuket Town and Cherngtalay.
A draft Accommodation Law, proposed on 29 September 2026, would replace the Hotel Act B.E. 2547 and introduce additional licence categories for homestays, hostels and short-term rentals.